
Glass substrates are gaining importance in AI chip packaging, with South Korea, TSMC and Intel accelerating investments in the technology.
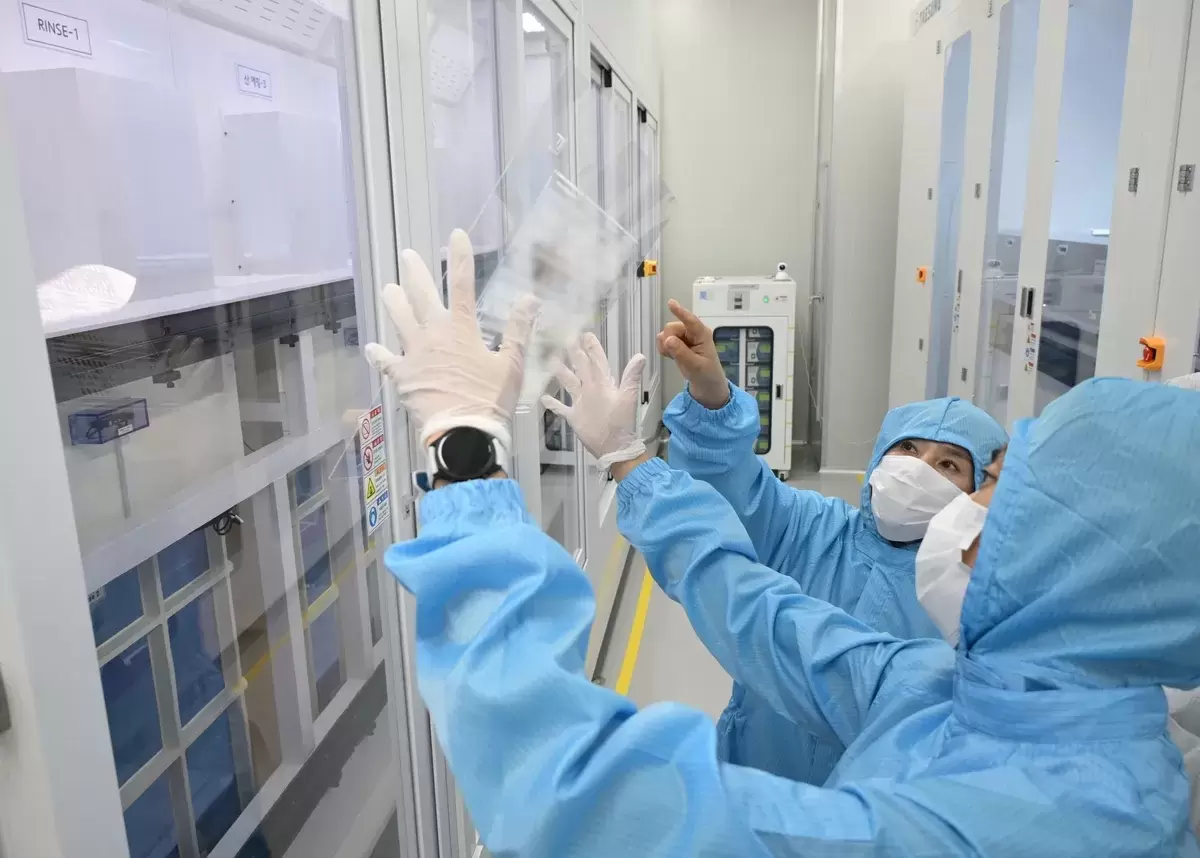
Glass addresses the limitations of conventional substrates
The race to develop chips capable of meeting the exponential growth of artificial intelligence is opening a new front: semiconductor packaging. Glass substrates are emerging as a potential alternative to the organic materials currently used, potentially reshaping competition between manufacturers such as TSMC, Samsung and Intel.
The development of AI processors is placing increasing pressure on conventional packaging technologies. As the number of transistors and memory components integrated into a single package continues to grow, traditional substrates face limitations related to thermal deformation, package size and the density of connections between chips.
Glass offers advantages for advanced packaging
Glass substrates offer several advantages in this environment. The material provides greater thermal stability and is less prone to warping when exposed to high temperatures. This stability makes it possible to develop larger packages and implement denser interconnections, both of which are particularly important for artificial intelligence accelerators and systems equipped with HBM memory.
Another advantage concerns communication between different chips. Research into optical communication integrated directly into substrates could help overcome some of the current bottlenecks in data transfer. The dimensional stability of glass also makes it suitable for highly dense interconnection structures.
An opportunity to challenge TSMC's dominance
The development of glass substrates is particularly significant for the South Korean semiconductor industry. TSMC has strengthened its leadership in the foundry market through advanced packaging technologies such as CoWoS, while Samsung Electronics has historically concentrated much of its strength on memory and semiconductor process technology.
The transition towards a new generation of packaging could now create an opportunity for South Korean companies to narrow this gap. The emergence of glass substrates could allow South Korea to compete not only in memory, but also in foundry and advanced chip integration.
The importance of this shift is closely linked to the evolution of HBM. As AI accelerators incorporate increasingly large amounts of memory, system performance depends not only on the individual dies but also on how they are interconnected and integrated within the package.
Intel, TSMC and Asian suppliers accelerate investment
The race is not limited to South Korea. Intel has identified glass substrates as a strategic technology and has invested in expanding its research and manufacturing capabilities. The company has also announced plans for a major glass-substrate manufacturing facility in India.
TSMC is also investigating the use of glass in future generations of advanced packaging. The Taiwanese manufacturer is working with partners across Asia, while Japanese and South Korean suppliers are seeking to secure positions in the emerging supply chain.
In South Korea, companies including Samsung Electro-Mechanics and SK Absolics are developing glass-based solutions. Samsung Electro-Mechanics has established a joint venture with Japan's Sumitomo Chemical to produce glass core, a key component of future substrates, with mass production targeted for 2027.
Commercialisation expected towards the end of the decade
Despite its potential, the technology still faces significant technical challenges. Glass is more brittle than many of the materials currently used, while processes such as drilling, metallisation and the creation of Through-Glass Vias (TGV) require extremely high precision.
Manufacturers and suppliers are therefore developing processes capable of improving production yields while maintaining mechanical and thermal stability. South Korean companies are already working on technologies for creating copper structures on glass and producing high-density substrates.
According to SEMI estimates, large-scale commercialisation of semiconductors using glass substrates could begin around 2028, with the market expected to experience very rapid growth. Industry forecasts point to an annual growth rate of more than 60%, potentially creating a market worth billions of dollars by 2040.
Packaging becomes critical in the AI era
The emergence of glass demonstrates how competition in the semiconductor industry is moving beyond chip manufacturing processes alone. As AI systems become larger and more complex, the ability to integrate processors, memory and high-speed interconnections is becoming equally important.
For South Korea, this transition represents a strategic opportunity. The country remains a global leader in memory and HBM, but strengthening its advanced packaging ecosystem will be essential to turning that advantage into broader technological leadership.
If glass substrates reach mass production within the expected timeframe, packaging could become one of the defining battlegrounds of the next generation of semiconductors. Competition between South Korea, Taiwan, Japan and the United States could therefore determine who controls one of the key technologies underpinning the next phase of the global chip industry.


Comments (0)