
Nearly $4 billion in new US paper mill construction is focused on packaging and tissue, with billions more in future projects planned.
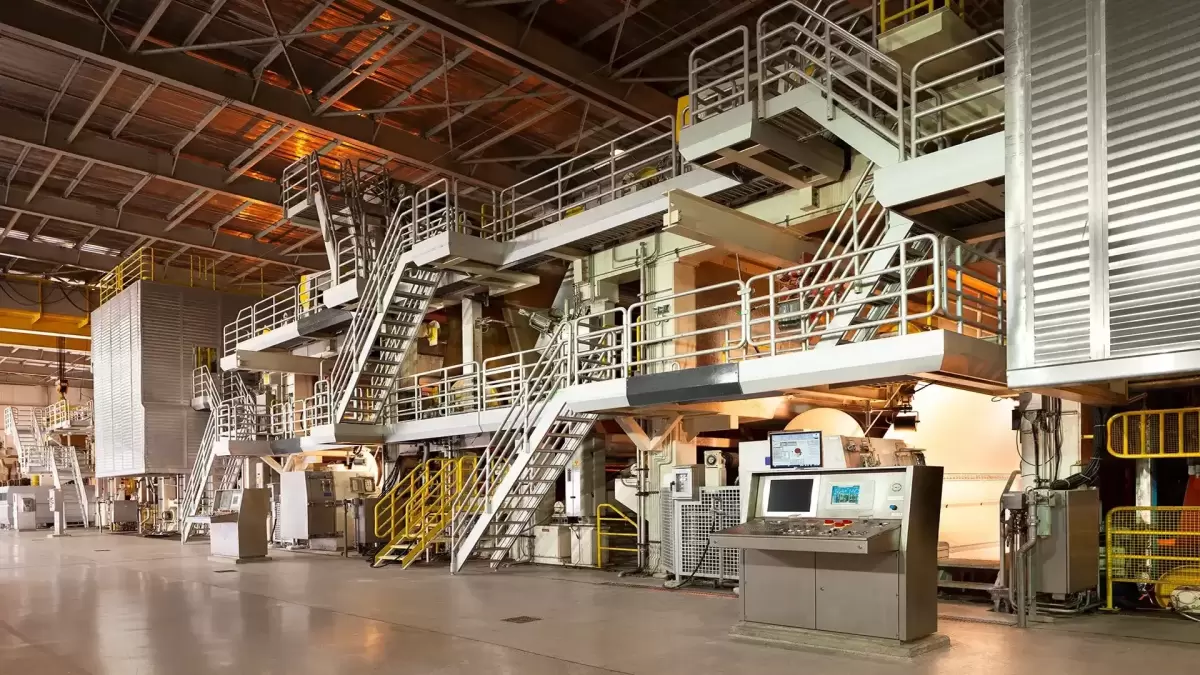
US paper investment concentrates on packaging and tissue
New paper mill construction in the United States is increasingly concentrated in packaging and tissue, with nearly $4 billion in active investment currently under construction. Data from Industrial Info Resources shows that these two segments now account for virtually all grassroot paper mills being developed across the country.
Although neither market is experiencing exceptionally rapid demand growth, packaging and tissue remain among the most stable areas of the US pulp and paper industry, encouraging producers to commit significant capital to new capacity.
Packaging attracts major mill investments
One of the largest packaging projects currently under development is Green Bay Packaging’s Project Powerpack in Morrilton, Arkansas. The company is investing around $1 billion in a new recycled linerboard mill as part of a wider upgrade that also includes modifications to recovery and biomass boilers and the installation of new power generation equipment.
The project reflects continued confidence in corrugated and fibre-based packaging, where linerboard demand remains supported by consumer goods distribution, food and beverage applications and e-commerce.
International Paper expands corrugated capacity
International Paper is also investing in its US packaging network. The company is completing a new corrugated box plant in Waterloo, Iowa, while simultaneously preparing to close an older facility in Carrollton, Texas.
It is also working on a sustainable packaging mill in Brandon, Mississippi, illustrating how producers are restructuring manufacturing networks by combining new capacity with the retirement or consolidation of older assets.
Future projects reinforce packaging dominance
The investment pipeline suggests that packaging will continue to dominate future grassroot paper mill construction. Industrial Info estimates that approximately $1.7 billion of additional new-build projects are currently in development across the US paper sector.
Of this amount, new packaging mills represent around $824 million, giving the segment the largest share of planned investment. Tissue projects account for approximately $675 million, while the remaining spending is largely associated with warehousing and distribution infrastructure.
Tissue also draws substantial capital
Current construction of new tissue mills already represents more than $2.2 billion in investment. Major projects include First Quality Enterprises’ new mill in Defiance, Ohio, which will feature two thru-air-dried tissue machines with capacity of approximately 60,000 to 70,000 tonnes per year each.
Kimberly-Clark is also progressing with a new tissue facility in Warren, Ohio, while Mexico’s Grupo Corporativo Papelera is completing a three-machine mill with seven converting lines in Texas.
Paper sector focuses investment on stable end markets
The concentration of new capacity in tissue and packaging illustrates a broader restructuring of the North American paper industry. Demand for traditional printing and writing papers has declined over time, pushing investment towards markets with stronger long-term fundamentals.
Packaging in particular continues to benefit from the shift towards fibre-based materials, recycled content and corrugated formats. The scale of current and planned investment suggests that producers expect these trends to support new mill capacity even in an environment of relatively moderate overall demand growth.



Comments (0)