
The next opportunity in sustainable packaging may not come from simply replacing conventional plastic with a greener material. It may come from understanding which bioplastic works for which application, where demand is developing, and how companies can build commercially viable products around it.
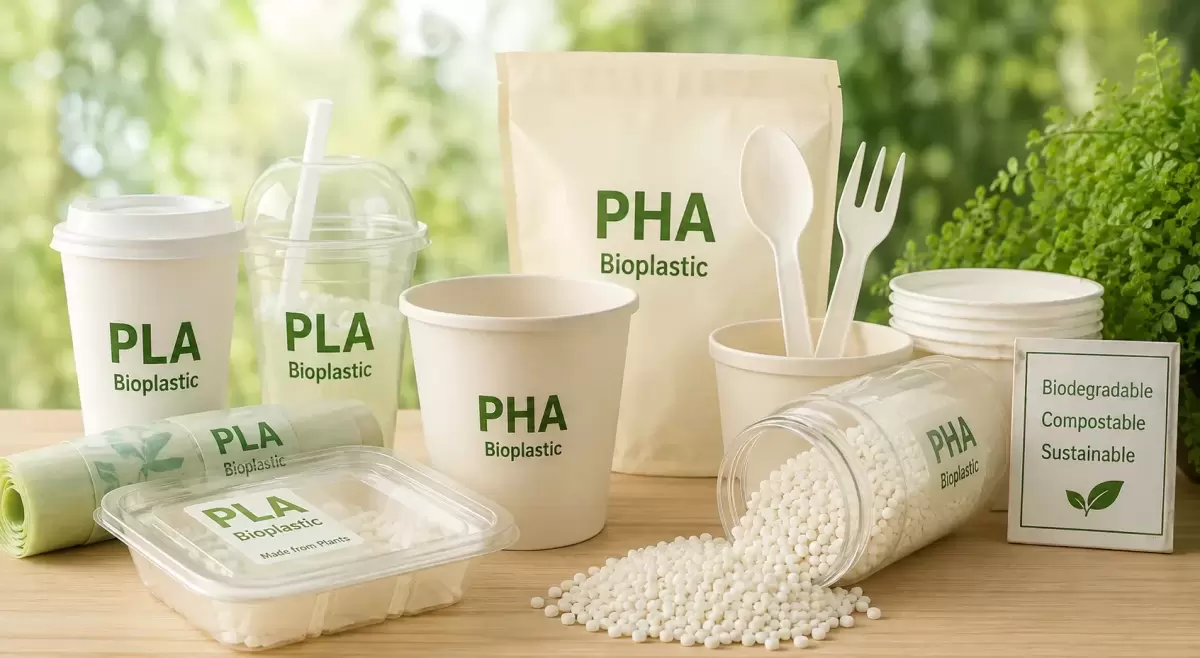
According to Towards Packaging, the global PLA and PHA bioplastic market was valued at USD 3.90 billion in 2025 and is projected to grow at a CAGR of 18.20% during 2025–2035. PLA represented the larger portion of the market with a 72% share in 2025, while PHA accounted for 28% and is expected to grow faster at a 20.8% CAGR.
For companies, these numbers point to something more significant than a sustainability trend.
They signal the development of a new commercial ecosystem involving resin manufacturers, packaging converters, food brands, healthcare companies, agricultural suppliers, 3D-printing businesses, and technology providers.
The real question is therefore not simply "Will PLA and PHA grow?"
It is:
Where can companies participate profitably in this growth?
The PLA and PHA Opportunity Is Becoming More DiversePLA and PHA are often discussed together, but they offer different commercial opportunities.
PLA has an established position because of its comparatively mature production infrastructure and compatibility with several existing processing technologies. It is already used in food containers, takeaway packaging, films, fibers, hygiene products, medical applications, and 3D-printing materials.
PHA is taking a different route.
Its biodegradability and biocompatibility make it attractive for applications where end-of-life performance or biological compatibility is especially important. PHA is being explored for food packaging, agricultural films, medical products, personal-care products, and other single-use applications.
This creates two different business strategies:
- PLA: scale existing applications and improve performance.
- PHA: develop higher-value applications where biodegradability and specialized performance justify the material cost.
For manufacturers, that distinction can influence investment, product development, and customer acquisition strategies.
Why PLA Still Gives Established Companies an AdvantagePLA held approximately 72% of the PLA and PHA market in 2025.
One reason is its established commercial ecosystem.
Companies entering the PLA value chain can benefit from existing production technology, processing knowledge, converter relationships, and end-use applications.
PLA can be processed through:
- Injection molding
- Extrusion
- Thermoforming
- Film production
- 3D printing
- Fiber production
- Other polymer-processing technologies
Injection molding represented the largest processing technology segment in 2025, with a 29% share. Pellets were the leading product form with a 41% share, demonstrating the importance of conventional resin supply chains.


Comments (0)