
India’s packaging market is moving beyond USD 100 billion as circularity, recycled content and automated sorting reshape materials and production.
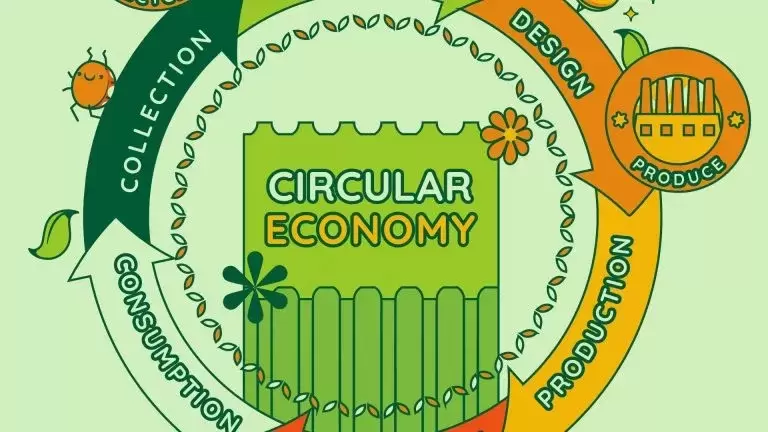
India’s packaging sector enters a major transformation
India’s packaging industry is undergoing a structural shift as circularity, regulation and automation increasingly influence material selection and investment decisions. The country’s packaging market is moving towards a valuation of more than USD 100 billion, with forecasts indicating that it could exceed USD 140 billion by 2029.
Food processing is one of the main forces behind this expansion, accounting for approximately 45% of domestic packaging demand. As India’s food manufacturing sector grows, packaging producers are being pushed to combine stronger barrier performance with recyclability, material efficiency and increasingly demanding compliance requirements.
Recycled content becomes central to packaging design
Extended producer responsibility requirements and recycled-content targets are changing the way plastic packaging is developed. Recycled material is increasingly being considered at the initial design stage rather than added later as a sustainability improvement.
This transition is also encouraging investment in domestic recycling infrastructure. India’s food-grade recycled PET capacity is expected to increase from around 750,000 tonnes per year to approximately 1.1 million tonnes as demand for recycled resin rises across beverage and food applications.
Flexible packaging retains a dominant position
Flexible packaging continues to represent the largest share of the Indian market, accounting for around 65% according to the industry data cited in the report. Lightweight structures and high-barrier films remain particularly important in a country where products must travel through extensive urban and rural distribution networks.
Maintaining shelf life while reducing material use is therefore a major development priority. Producers are increasingly exploring recyclable flexible structures, mono-material designs and technologies that can combine lower environmental impact with the performance required for food applications.
Paper and bio-based materials gain ground
Paper and bio-based substrates are also seeing stronger adoption, particularly in takeaway food, cloud kitchens and quick-service restaurants. These materials represent approximately 38.6% of India’s sustainable packaging segment according to the figures cited.
The shift reflects both regulatory pressure on single-use plastics and growing demand from brands for packaging that can communicate stronger environmental credentials. However, barrier performance, cost and local waste infrastructure remain important considerations when replacing conventional plastic structures.
AI-driven sorting supports recycling economics
Technology is becoming another important part of India’s circular packaging transition. Recyclers and processors are increasingly adopting locally manufactured automated sorting equipment, including AI-driven optical systems capable of separating materials with greater accuracy.
Domestic production of this equipment can reduce dependence on imported machinery and lower investment costs for medium-sized recycling companies. Higher-purity sorting is particularly important for producing recycled materials capable of meeting demanding food-contact and manufacturing specifications.
Smart packaging expands alongside circularity
The transformation is not limited to materials. Indian packaging is also incorporating more digital technologies, including QR codes, batch tracking and authentication tools designed to improve supply-chain transparency and consumer information.
These technologies can support traceability, anti-counterfeiting and recycling communication while allowing brands to connect physical packaging with digital product information. As regulations and customer expectations evolve, packaging is increasingly becoming both a protective format and a data platform.
Growth increasingly linked to circular performance
India’s packaging expansion is therefore becoming closely connected to its ability to improve material recovery, recycled-content availability and production efficiency. Continued investment in recycling, automated sorting and sustainable materials will be critical as packaging demand grows alongside the country’s food and consumer goods industries.
The development of a larger domestic circular economy could also reduce dependence on virgin materials while creating new opportunities for converters, recyclers and packaging technology suppliers across one of the world’s fastest-growing packaging markets.

Comments (0)