
European paper and board output fell 1.6% in 2025, while packaging remained resilient and the industry warned that ETS changes could curb investment.
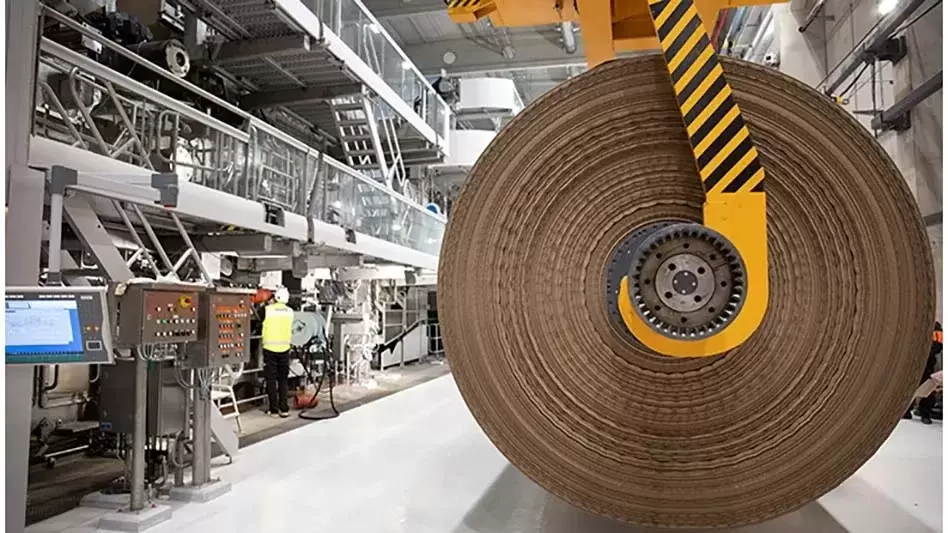
European paper and board production declines in 2025
European paper and board production fell by 1.6% in 2025 to approximately 77.4 million tonnes as manufacturers continued to face high energy costs, weak economic conditions and stronger competition from producers outside the region.
According to the latest figures from the Confederation of European Paper Industries, the overall decline masks significant differences between market segments, with packaging grades remaining comparatively resilient while graphic papers continued their structural decline.
Packaging remains one of the strongest segments
Production of packaging papers remained broadly stable during the year, reinforcing the segment’s importance to the European paper industry. Demand linked to e-commerce, logistics, food and consumer goods continues to support fibre-based packaging despite wider industrial weakness.
However, performance was not uniform across all packaging grades. Cartonboard production declined by 5.4% in 2025, reflecting softer demand and challenging market conditions in some end-use sectors.
Containerboard continues to dominate production
Containerboard remains the largest segment within European paper and board production, with output of around 32.9 million tonnes in 2025. The material represents approximately 43% of total production and continues to underpin the corrugated packaging supply chain.
Its strong position reflects the continued importance of corrugated boxes across transport, warehousing, retail and e-commerce, where fibre-based packaging remains a widely used and established format.
Recycling rate moves above 2030 target
Europe’s paper and board recycling rate reached approximately 76.4% in 2025, exceeding the 76% target established by the European paper value chain for 2030.
Paper mills used more than 45 million tonnes of recovered paper during the year, while close to 54 million tonnes were collected for recycling. Recovered fibre therefore continues to represent a major raw material source for packaging papers and board.
Carbon performance continues to improve
The industry has also continued to reduce its environmental footprint. Direct carbon emissions have fallen significantly over recent decades, while emissions per tonne of paper and board produced have declined as mills increase energy efficiency and the use of biomass and renewable electricity.
This progress has allowed the sector to position fibre-based packaging as part of Europe’s broader circular economy and bioeconomy strategies, combining renewable raw materials with high recycling rates.
EU ETS changes raise competitiveness concerns
Despite these environmental gains, Cepi has warned that proposed changes to the European Union Emissions Trading System could weaken the business case for further decarbonisation investment.
The association estimates that changes to free-allocation benchmarks and eligibility rules could reduce planned investment capacity by around €1 billion annually between 2026 and 2030. Energy-intensive paper mills already face higher operating costs in Europe than in several competing regions.
Biomass rules create additional pressure
One of the industry’s concerns relates to a 95% biomass threshold used within the ETS framework. Paper mills have invested heavily in recovering energy from biomass and production residues, but operators argue that the new threshold could penalise facilities that have already made significant progress towards lower-carbon production.
Smaller and medium-sized mills may face particular challenges because the administrative and capital costs associated with further decarbonisation can represent a larger proportion of available investment resources.
Packaging resilience depends on industrial competitiveness
The 2025 figures underline the contrast between strong circularity performance and growing industrial pressure. Paper-based packaging continues to benefit from established recycling systems and demand for renewable materials, but its long-term competitiveness will also depend on energy costs, investment conditions and manufacturing capacity remaining viable within Europe.
For packaging producers and buyers, the challenge will be to maintain strong recycling and carbon performance while ensuring that regulatory costs do not accelerate the shift of paper and board production to regions outside the European market.

Comments (0)